Top Stories
CMS billing rule clarifications are cutting Medicare reimbursement for rural clinics relying on nurse practitioners, threatening clinic finances and care access.
Grocery delivery growth in suburbs masks a quieter crisis – rising food insecurity among working households that delivery platforms never reach and statistics rarely capture.
Student loan delinquencies are climbing fast as repayment pause protections expire, hitting borrowers hardest with servicer failures, frozen relief plans, and credit score fallout.
Tariff stockpiling earlier this year left U.S. importers holding excess inventory, and now that glut is quietly suppressing Q3 import demand as companies wait it out.
Private credit funds have raised over $1.4 trillion, displacing banks as middle-market companies seek faster, more flexible financing solutions.
Egg prices are falling after record highs, but grocery retailers face a harder problem: shoppers who changed habits during the crisis may not come back.
The CFPB’s $8 credit card late fee cap remains blocked by federal courts over a year after its finalization, leaving cardholders paying fees up to $32 while legal and political battles stall relief.
State attorneys general are investigating hospital billing middlemen for practices that may inflate costs and harm patients. Here’s what’s driving the crackdown.
As subsidy programs face cuts and pandemic-era stabilization funding expires, child care deserts are widening – pulling working parents, especially mothers, out of the labor force.
Municipal bond defaults are rising as state aid cuts leave small cities and districts unable to cover debt payments – a slow-moving credit story gaining speed.
AI-driven data center expansion is pushing natural gas demand higher as power grids strain to meet relentless 24/7 load. Utilities, producers, and ratepayers are all feeling the pressure.
Regional banks are pulling back from middle-market and commercial lending, and private credit funds are rapidly filling the void – with real consequences for borrowers and risk.
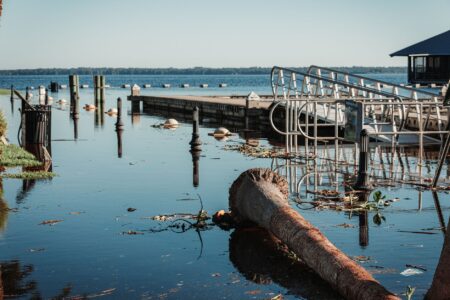
Private flood insurers are exiting coastal markets, leaving homeowners reliant on an underfunded federal program facing its own pricing crisis and growing coverage gaps.